Services
Roof Insurance ClaimsBased in Haslet, TX
Help with a hail or wind claim, from the free inspection through the adjuster and change orders to the insurance check.
Get a Free EstimateInsurance Claims
What this job involves on a North Texas roof.
Whether it is your first insurance claim or you have been through one before, the process is usually confusing, and it can start to feel like your insurance company is not looking out for you the way you expected. Power House works for you and not for your insurance company, and if a question comes up at any point, your project manager is there to answer it.
It starts with a free inspection to find out whether there is storm damage worth claiming. If there is, you report it to your insurance company and an adjuster comes out to look. Chances are we use the same kind of estimating software and pricing as your insurance company, which lets your project manager and the adjuster assess the damage, the materials and the labor from the same starting point and agree on a price for the work.
What a job includes
- Free inspection for storm damage
- Estimates in the same kind of pricing software insurers use
- Scope and price agreed with your insurance company
- Change orders submitted to your adjuster
- Your project manager at a re-adjustment
- Help with a check made out to you and your mortgage company
- An agreement that is void if the claim is denied
How It Works
Free inspection
We get on the roof and look for damage and whether it is storm-related, so you can file a timely claim with your insurance company.
Scope and price
On an insurance job, the work is done at the price your insurance company approves for the scope. On a job you are paying for yourself, the inspection and the quote are free and carry no obligation.
The work
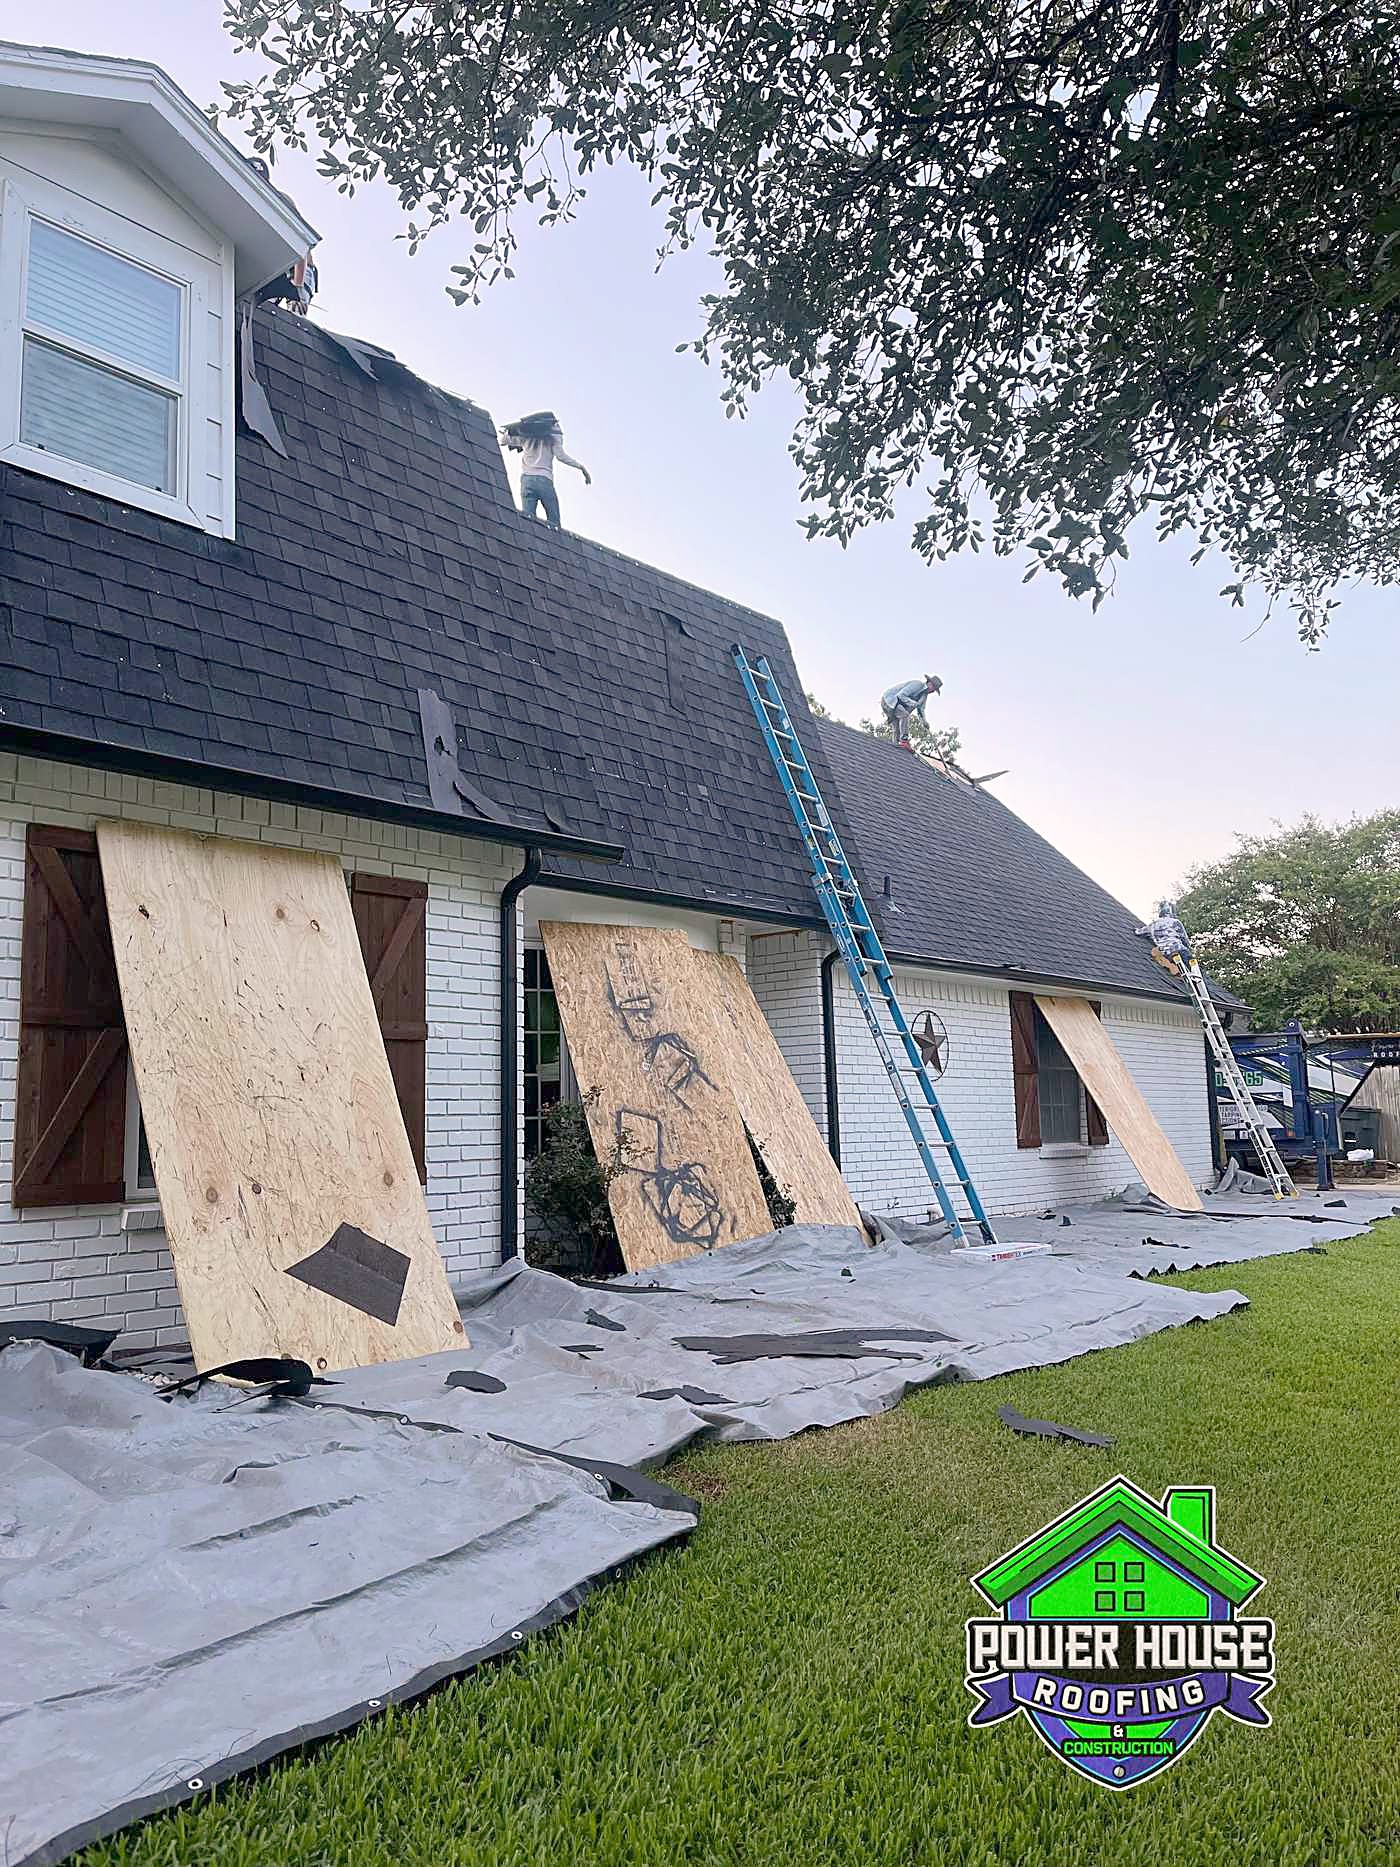
The crew tears off the old roof down to the decking, installs the new roof system and cleans up the property before leaving.
Change orders and the check
If more damage turns up once the roof is open, your project manager takes it to the adjuster as a change order, and walks you through the insurance check when your mortgage company is on it.
The Difference
The details that decide how long it lasts.
Your insurance company may suggest getting three estimates and sending them in. You are not required to. You are allowed to choose whichever contractor you want to do the work on your property, and once the scope and price are agreed with your insurer, the job is done at that agreed price. That is what "per insurance proceeds" means when it appears on your paperwork.
Sometimes more damage turns up once construction begins, or the scope changes for another reason no one could see beforehand. When that happens, your project manager submits a change order to the insurance company and deals directly with your adjuster to get it approved and paid. It is standard procedure and insurance companies expect it. Funds released by a change order are part of the job cost, the same as any other insurance payment.
If your adjuster denies the claim, you can request a re-adjustment and have your project manager there when the adjuster looks again, to make sure every piece of storm-related damage is pointed out. If it is denied a second time, your insurance company's appeal or grievance process is the next step. Any agreement with Power House is contingent on insurance approval and void if the claim is denied, and you are not liable for any payment in that case.
The check itself often carries your mortgage company's name as well as yours, because the lender has a stake in the house being repaired. If your mortgage is with a local bank, some branches can endorse the check for you; other lenders need it mailed to them, and some send an inspector to confirm the work is done. Your project manager walks you through whichever applies to your loan.
Get a Free EstimateBefore You Call
Insurance Claims, answered.
Do I still have to pay my deductible?
Yes. Texas law requires the homeowner to pay the deductible on an insurance-funded roofing job and bars a contractor from waiving, absorbing or rebating it. It is worth knowing before anyone offers otherwise.
What does "per insurance proceeds" mean?
It means the work is done at the price agreed between us and your insurance company. Because the scope and the price are settled with the insurer, you are not left comparing a contractor's number against the adjuster's.
What is a change order?
A change to the agreed scope and price once work is under way, usually because more damage was found when the old roof came off. Your project manager submits it to the insurance company and works with your adjuster to get it approved and paid.
What if my claim is denied?
Request a re-adjustment and have your project manager present when the adjuster reassesses. If it is denied again, look into your insurer's appeal process. An agreement with Power House is void if the claim is denied, so you owe nothing.
Why is my mortgage company on the insurance check?
Because the lender has an interest in the property being repaired. Some local banks can endorse the check at a branch, while other lenders need it mailed in and may send an inspector to confirm the work was done.
More from Power House Roofing & Construction
Insurance Claims
Insurance Claims, handled from the first inspection to the final nail.
Let's Work Together
Book a free roof inspection.
Call us or send the form, and we will set up a time to look at the roof.
Power House Roofing & Construction, LLC 12512 Willow Springs Rd Ste 100, Haslet, TX 76052 (817) 720-6465 · sales@